

Nu: Everyday mobile banking
by Nu
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 100.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
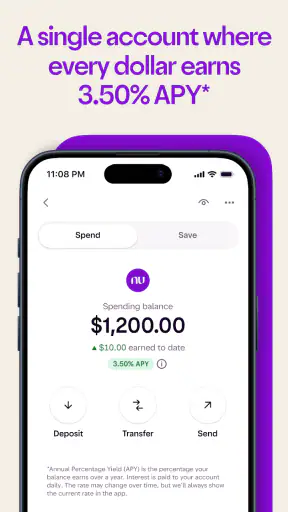
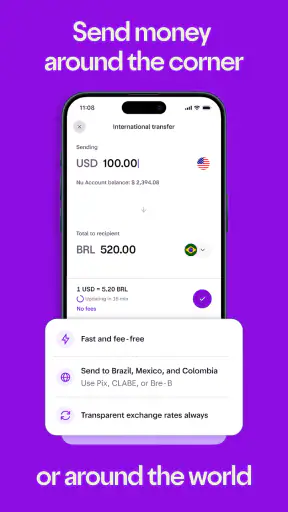
 Analysis by Getfullapps
Nu: Everyday mobile banking is the kind of finance app I would judge less by flashy extras and more by how clearly it lets me understand and control my money. Developed by Nu, it is free, rated for Everyone, and has become a very large mobile banking service, with more than 100 million installs and an average score of 4.7 from roughly 5.9 million ratings. Those figures suggest that many people find it useful, but they do not remove the need for careful checking when an app is connected to personal finances.
My first impression is that Nu is aimed at people who want daily banking to happen from a phone rather than through repeated branch visits or complicated desktop tools. The app’s role is practical: it gives users a central place to interact with their Nu financial relationship, review activity, and make routine decisions. That focus makes it more approachable than a traditional banking website, especially for someone who prefers quick, visual access to account information.
At the same time, I would not treat a polished mobile experience as proof that every financial decision is automatically safe. A banking app deserves a slower first setup than a social app. I would install it only from the official Android or iOS store, check that the developer shown is Nu, and read each permission or security prompt instead of tapping through everything. The most important trust feature is not convenience; it is knowing what I am authorizing at each step.
How Nu builds trust through everyday control
Nu has been available since April 25, 2014, and its scale is easy to notice: the service says it is trusted by over 140 million people. That broad reach can reassure a new user that the app is not an obscure experiment, but popularity should remain only one part of the decision. I still want to see understandable account controls, clear activity information, and a straightforward way to react when something looks wrong.
When I review a finance app, I begin with the moments that matter after the initial sign-in. Can I quickly recognize a recent transaction? Can I distinguish a normal payment from something unfamiliar? Can I find the settings that affect access without searching through unrelated menus? These details are more valuable than decorative design because they determine how quickly I can notice a problem.
Nu works best for someone who wants to check their finances frequently in short sessions. Instead of waiting for a monthly statement, I can make a habit of opening the app after a purchase, checking recent movement, and closing it again. That routine is especially useful for people who lose track of small card payments or want a tighter connection between spending and their available balance.
A useful workflow is to review the account before making a larger purchase, then check the activity afterward. This creates two reference points: what I expected to have available and what actually changed. If the result does not match, I can investigate while the purchase is still fresh in my memory. That is a more reliable habit than trying to reconstruct several weeks of spending later.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I also like the idea of separating “checking” from “acting.” I can open the app simply to inspect activity without immediately transferring money or changing an account setting. That small mental separation reduces impulsive decisions. In a finance app, the ability to pause and verify is just as important as the ability to complete a task quickly.
What account control should look like in practice
For me, good control means that important actions are visible, deliberate, and easy to review afterward. Before confirming a payment or transfer, I would check the destination, amount, and timing rather than relying on memory. If the app presents a confirmation screen, I would use it as a final inspection rather than treating it as a formality.
I would also keep my phone’s operating system updated and protect the device with a strong screen lock. Nu cannot compensate for an unlocked phone, a shared device, or a password reused across several services. The safest experience comes from combining the app’s available account controls with sensible device habits.
Another practical point is notification discipline. Alerts can help me notice account activity quickly, but I would avoid displaying sensitive financial details on a lock screen if other people might see the phone. The right balance is to receive enough information to prompt a check without exposing more than necessary in a public place. This is a small setting choice, but it changes the privacy of everyday use.
I would never approve a sign-in request or payment prompt simply because it appears while I am busy. If I did not start the action myself, I would stop and open the app directly instead of following an unexpected message. This is particularly important with mobile banking because a convincing notification can create pressure to act before thinking.
Data-sensitive moments deserve extra attention
Finance apps naturally handle information that needs careful treatment. I would pay close attention during registration, identity checks, device changes, password recovery, and any request for access to information outside the basic banking task. These are the points where users are most likely to share sensitive details quickly because they want to finish setup or regain access.
My approach would be simple: read the explanation attached to each request, grant only what is needed for the action I am taking, and revisit permissions later if the phone allows it. I would not assume that a permission is harmless just because the app is well known. Trust should come from visible choices and understandable explanations, not from the app’s popularity alone.
I would also avoid using public Wi-Fi for sensitive account actions when a private connection is available. If I had to use a shared network, I would postpone anything important until I could connect more safely. This is not a criticism of Nu specifically; it is a sensible boundary for any app that gives access to financial information.
A realistic example is paying for a household purchase while standing in a busy café. I might open Nu to check whether the money is available, but I would avoid leaving the account open while distracted, and I would make sure the screen is not visible to people nearby. Afterward, I would check the activity only if the transaction details were clear enough to recognize. Convenience is helpful here, but awareness prevents convenience from becoming carelessness.
Recovery is another data-sensitive moment. If I lose my phone or change devices, I would use only the official recovery path inside the app or its recognized support channels. I would not send account details to someone who contacts me unexpectedly and claims to be helping. A trustworthy banking routine includes knowing how I will regain access without handing control to an unverified person.
Where user agency matters most
The strongest reason to choose a mobile bank is usually agency: I can see what is happening and respond without waiting for office hours. Nu fits that preference for people who want their financial life close at hand. I can build a habit of checking activity, questioning unfamiliar movement, and making decisions while the information is current.
However, agency also means accepting responsibility. A notification is not a substitute for reading a transaction. A high rating is not a substitute for checking the recipient. And a fast confirmation is not necessarily a good confirmation. I would recommend Nu to someone who is willing to stay involved, not to someone looking for a completely hands-off way to manage money.
One of my favorite practical habits with any banking app is a weekly review that is short but intentional. I would look for unfamiliar activity, recurring charges I no longer need, and purchases that were larger than expected. The point is not to obsess over every small movement; it is to create a regular checkpoint so that mistakes do not remain invisible for too long.
Another useful habit is keeping a separate note of pending financial commitments, such as bills or planned purchases, rather than treating the visible balance as spending money. The app can show the current account picture, but I still need to account for what I have already promised to pay. This distinction helps prevent the common mistake of confusing “available right now” with “safe to spend.”
For families, the decision requires more thought. A parent may appreciate mobile access, but I would be cautious about sharing a device, passcode, or login details. Shared access can blur responsibility and make it harder to identify who performed an action. Each person should use the access arrangement intended for them, and sensitive credentials should not become a casual household shortcut.
Nu compared with traditional banking habits
Compared with a conventional branch-centered bank, Nu is more attractive when speed and phone access matter. I can check information during the day rather than planning a visit or waiting to use a desktop computer. That makes it a natural fit for people who already organize much of their life through a smartphone.
The trade-off is that a phone-first experience may feel less comfortable when I need extended help, have limited connectivity, or prefer speaking to a person before making an important decision. Someone who values a nearby branch, paper documentation, or a more traditional service relationship may be happier with a conventional bank, even if the mobile app is less convenient.
Compared with a basic wallet or payment app, Nu is better suited to someone who wants a broader banking relationship rather than a single-purpose way to send money or pay. A wallet can be simpler for occasional transactions, while a bank app is more relevant when I want a continuing view of account activity and financial decisions. The best choice depends on whether I need banking access or merely a payment tool.
Compared with a budgeting app, Nu should not automatically be treated as a complete financial planning system. A budgeting tool may be preferable for someone whose main goal is category analysis, long-term planning, or combining information from several institutions. I would choose Nu for direct day-to-day banking access and use another tool when detailed planning is the priority.
That distinction prevents disappointment. Nu can be valuable without replacing every other financial tool. I would judge it by how well it supports the tasks I actually perform: checking activity, making ordinary decisions, and keeping control of access. If my needs move toward complex investing, business accounting, or multi-account analysis, I would compare specialized services instead of assuming one mobile bank should do everything.
Who should use it, and who should pause
I think Nu is a strong candidate for a person who wants free mobile banking, prefers self-service, and is comfortable reviewing financial activity on a phone. The Everyone age rating also makes the app broadly approachable, although age suitability does not remove the need for responsible account supervision or careful handling of credentials.
It is particularly suitable for someone building better financial habits. The phone is usually nearby, so checking a recent purchase can become part of the normal routine rather than an occasional chore. That immediacy can help a user notice errors sooner and feel more connected to everyday spending.
I would pause before choosing it if I strongly prefer face-to-face banking, dislike managing security settings, or often use devices that other people can access. I would also compare alternatives if my main need is advanced budgeting, detailed financial reporting, or a service model centered on personal assistance. The app’s convenience is most valuable when its mobile-first approach matches the way I already work.
The large audience and 4.7 average rating are encouraging signs, but they are not a personal guarantee. A banking app can suit millions of people and still feel wrong for a particular workflow. I would install it because its approach fits my needs, then spend time checking the controls and privacy choices before relying on it for regular financial activity.
My cautious verdict
Nu: Everyday mobile banking makes sense to me as a practical, phone-centered finance app for people who want frequent access and direct control over everyday banking. Its free price removes an obvious barrier to trying it, and its long presence, broad adoption, and strong average rating make it worth considering. Still, I would keep my expectations specific: it is a tool for managing a banking relationship, not a replacement for financial judgment.
My recommendation comes with a clear condition: use it actively, not passively. Check the details before confirming actions, protect the device, review sensitive requests, and treat unexpected messages with suspicion. Those habits make the app more useful because they turn quick access into informed control.
If I wanted a convenient mobile banking companion and was comfortable handling security and account decisions myself, I would give Nu a serious look. If I wanted branch-based support, extensive planning features, or a specialized budgeting workspace, I would compare other options first. Nu is at its best when convenience and personal responsibility work together.
Pros
- No-fee digital account with transparent everyday banking features.
- Easy bill payments, transfers, and card controls from one app.
- Useful spending insights help users monitor their financial habits.
- Virtual card support adds convenience for online purchases.
- Customer support and security tools are available directly in the app.
Cons
- Some features and fees vary depending on the user's country.
- Cash deposits and branch-based services are generally unavailable.
- Account approval may require identity checks and supporting documents.
- App features can depend on having a stable internet connection.
- Savings and credit options may not be available to every user.
FAQs for Nu: Everyday mobile banking
What is Nu: Everyday mobile banking?
Nu: Everyday mobile banking is the official app from Nubank, designed to let customers manage everyday financial services from a smartphone. Depending on the country and account type, it may provide access to checking or savings features, transfers, bill payments, cards, loans, spending information, and other financial products. The exact tools available can vary by location and eligibility.
Is Nu: Everyday mobile banking safe to use?
The app includes standard security measures such as account authentication, device verification, transaction confirmations, and controls for cards and payments. Users should still protect their phone, use a strong device passcode, avoid sharing verification codes, and install the app only from an official app store. Security features and requirements can differ according to the user’s country and account.
Can I open a Nubank account directly from the app?
In supported markets, new customers can usually begin the registration process inside Nu: Everyday mobile banking by providing personal information and documents required for identity verification. Approval is not automatic, since Nubank may review the application and apply local eligibility rules. You should also confirm that the app is officially available in your country before starting.
What banking services can I manage with the app?
The available services depend on your country, account, and Nubank products, but the app is intended to centralize common financial tasks. These may include checking balances and statements, sending transfers, paying bills, managing a debit or credit card, viewing purchases, adjusting card settings, and exploring credit or savings options. Some features may require separate approval.
Is Nu: Everyday mobile banking free to download and use?
The application is generally free to download from the official Android or iOS stores, but using the app does not mean every financial service is free. Certain transactions, withdrawals, international operations, credit products, late payments, or other services may involve fees, interest, taxes, or local charges. Always review the terms shown in the app before confirming an operation.

Nu: Everyday mobile banking
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via meajuda@nubank.com.br, visit https://www.nubank.com.br, or review their https://nubank.com.br/contrato/politica-privacidade/.










